Long Established Coney Island Restaurant
Business Overview
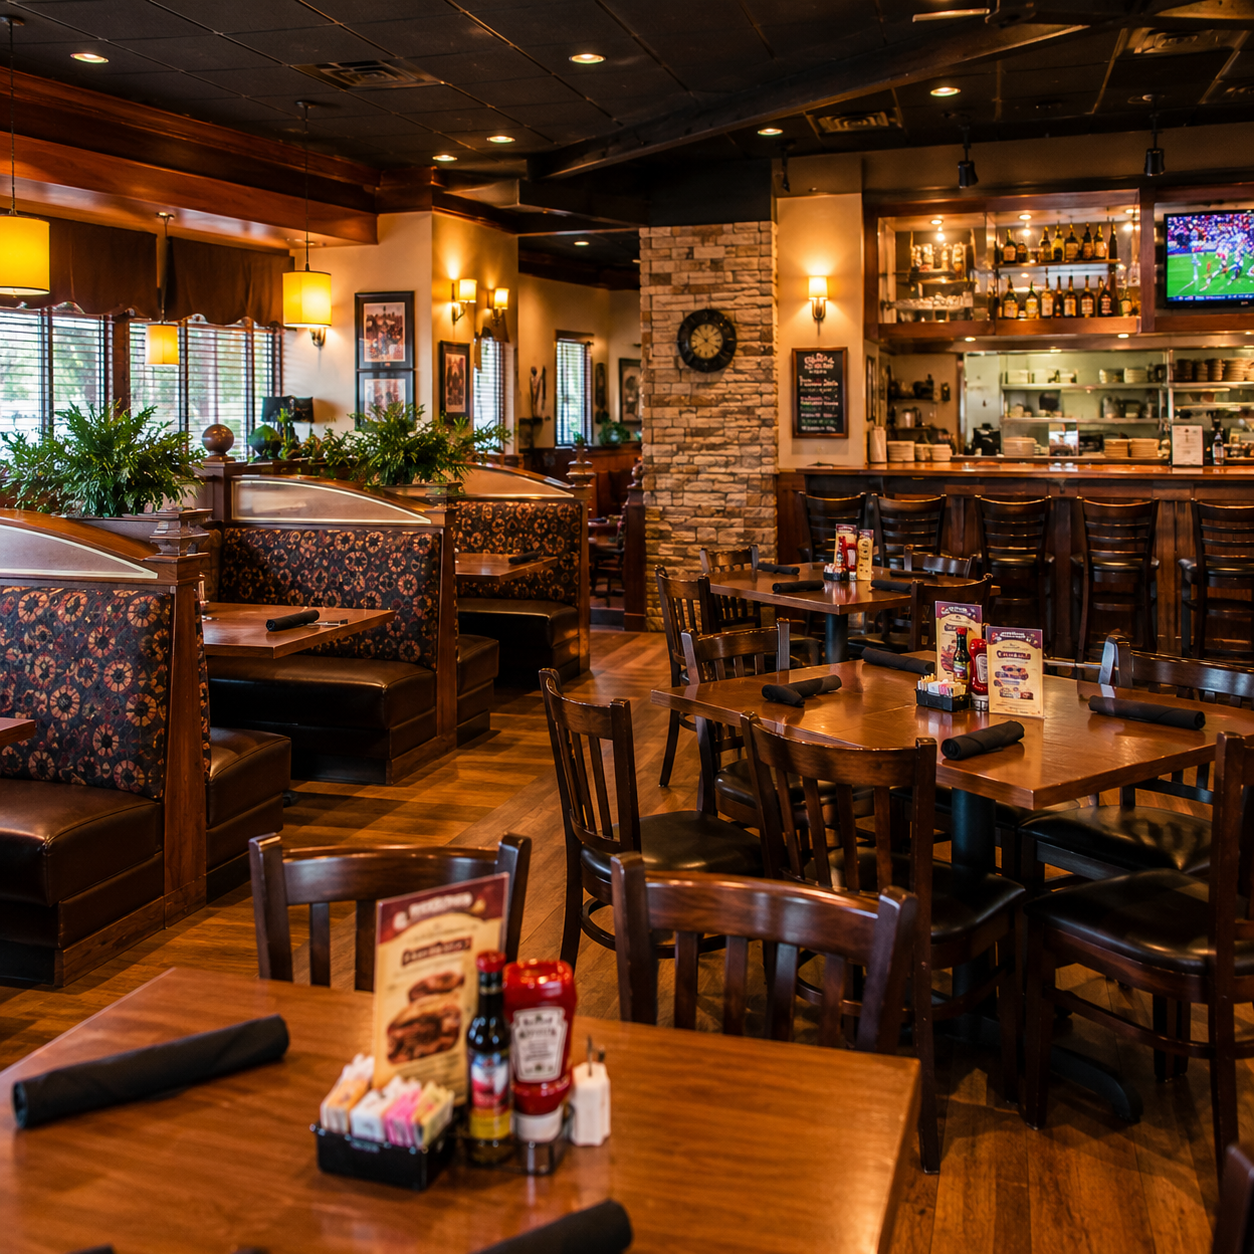
This well-established casual dining restaurant is located in a busy commercial corridor within a densely populated suburban market in Southeast Michigan. For more than 25 years, the business has built a strong reputation for quality food, friendly service, and customer loyalty, generating consistent sales from both repeat patrons and new customers throughout the surrounding trade area.
The restaurant operates from a freestanding approximately 3,500-square-foot facility situated on approximately one-half acre with ample customer parking. The dining room accommodates approximately 114 guests and is supported by a fully equipped commercial kitchen capable of serving a broad menu offering across multiple dayparts. The operation is well-positioned to support dine-in, carryout, catering, and other revenue opportunities.
The business is owner-operated and supported by an experienced staff, providing a turnkey opportunity for a new owner. Significant opportunities exist to further grow revenue through expanded marketing initiatives, enhanced online ordering and delivery platforms, increased catering efforts, and other operational improvements.
This offering is ideally suited for an owner-operator, family business, experienced restaurateur, or hospitality entrepreneur seeking an established operation with a proven history, loyal customer base, and substantial upside potential.
The seller is pursuing personal and family-related priorities and is committed to assisting with a smooth transition to new ownership.
Financial Overview
Verified — TaxBusiness Details
1999
1999
1 FT
Mon-Sat 6:30am-9pm, Sun 7am-8pm
Food Service, Sales tax
Family Restaurant
Occupancy & Real Estate
Downriver
Not Included
Leased
Through July 31, 2029
7/31/2029
5 years
Training & Transition
Two weeks
Reason for Sale
Family Issues
Frequently Asked Questions
Start by asking whether this is the type of business that actually fits your interest, background, goals, and available time. The first question is not just "does this business make money?" It is also "would I want to own and operate this?" After that, review the financial summary, asking price, SDE or EBITDA, business description, lease or real estate information, owner involvement, staff structure, reason for sale, and key business details. If the business looks like a potential fit, you can submit a request for more information. From there, we can confirm whether we already have an NDA on file or help you complete one before releasing additional details. A listing page should help you decide whether to take the next step. It is not meant to answer every question you will ever have before breakfast.
SDE stands for Seller's Discretionary Earnings. It is commonly used for smaller Main Street businesses where the owner is actively involved in the operation. SDE is intended to show the total financial benefit available to one working owner. For many small businesses, owners may have personal, discretionary, non-recurring, or owner-specific expenses running through the financials. SDE adds back certain expenses that a new buyer may not incur, along with certain non-cash expenses such as depreciation and amortization. This helps buyers better understand the normalized earning power of the business. EBITDA stands for Earnings Before Interest, Taxes, Depreciation, and Amortization. EBITDA is more commonly used for larger or more sophisticated businesses, especially when there is management in place and the financials already include appropriate management compensation. The major difference is that SDE typically adds back one owner's compensation and benefits, while EBITDA usually assumes management compensation is already included in the operating expenses. In plain English: SDE is usually more common for owner-operated businesses. EBITDA is usually more common when the business is large enough to be viewed more like an organization than a job with employees.
In many cases, yes. Asking price is the seller's target price, but final terms depend on buyer interest, financing, deal structure, due diligence, and negotiation. A strong offer is not just about price. Sellers also look at down payment, financing certainty, buyer qualifications, contingencies, closing timeline, transition expectations, and how serious the buyer appears. A lower offer with clean terms and a qualified buyer may be more attractive than a higher offer that has more holes than a gas station umbrella.
Some listings include real estate, some offer real estate separately, and others are lease-only opportunities. The listing should indicate whether real estate is included, available, or not applicable. Buyers should pay close attention to whether the reported cash flow accounts for rent. In many cases, even if real estate is available or included, the business cash flow is shown after accounting for rent that the business would pay for occupying the property. If you buy the business and the real estate together, you may effectively receive the benefit of that rent as the property owner. Said differently, the business may pay rent, but if you own the property, that rent may come back to you through the real estate ownership structure. Buyers should review the real estate structure carefully with their lender, CPA, attorney, and advisors.
Most business sales include some form of post-closing transition assistance, but the length and depth vary by transaction. That assistance is usually focused on transitioning the business, not teaching the buyer an entire trade from scratch. A seller may help with vendor introductions, employee handoff, customer transition, basic systems, POS training, operational routines, and general guidance. But if you buy an electrical contractor and you are not an electrician, the seller is not going to turn you into one in two weeks. That is not training. That is a miracle with a clipboard. Buyers should understand what skills are required to operate the business and whether they personally have those skills, can hire those skills, or can manage people who do.
Employees are generally expected to continue working after a sale, but they cannot be legally forced to stay. One of the reasons confidentiality is so important before closing is to avoid unnecessary employee concern or disruption. After closing, employee retention becomes part of the buyer's responsibility. Most employees want stability, fair treatment, clear communication, and confidence that their compensation and work environment are not going to suddenly get worse. A buyer who comes in respectfully, avoids unnecessary immediate changes, and follows evolution instead of revolution will usually have a much better chance of retaining employees. If a buyer walks in on day one acting like a dictator with a spreadsheet, employees may start updating resumes before lunch.
In many cases, a buyer may be able to visit the business discreetly as a customer, especially if it is a customer-facing location. However, buyers must not speak with employees, ask suspicious questions, disclose that the business is for sale, or approach the seller directly unless the visit has been coordinated and approved. Formal site visits are usually coordinated after a buyer has been screened, signed an NDA, reviewed preliminary information, and shown serious interest. Confidentiality matters. A casual visit should not turn into a detective mission with bad acting.
Before submitting an offer, you should ask enough questions to understand the business, the general financial performance, the owner's role, employees, lease or real estate terms, reason for sale, financing potential, transition expectations, and whether the opportunity fits your goals. Our goal is to provide enough information for a serious buyer to decide whether they want to move forward. However, there is a line between pre-offer review and due diligence. Before an offer, it is reasonable to clarify major issues. After an offer is accepted, due diligence is where the buyer verifies the information in detail, reviews supporting documents, examines expense lines, checks contracts, evaluates records, and digs deeper into the business. In simple terms: before the offer, you decide whether the opportunity makes sense. During due diligence, you verify that it is what it was represented to be.
Submit a request for more information through the listing page or contact Capital Business Brokerage directly. We will confirm the listing you are interested in, determine whether an NDA is already on file, and guide you through the next step. Depending on the listing and your qualifications, you may receive additional information, speak with a broker, ask clarifying questions, request a seller call, or prepare an offer. The cleaner and more complete your buyer information is, the faster the process usually moves. Serious buyers tend to get more serious traction.
Information regarding this business has been provided by the Seller and other sources and is believed to be reliable, but has not been independently verified by Capital Commercial Group, Inc., also known as Capital Business Brokerage. All financial, operational, lease, real estate, inventory, equipment, licensing, and other information is subject to buyer verification and may change without notice. This listing is for informational purposes only and is not an offer or binding agreement. Buyers should conduct their own due diligence and consult their own legal, tax, accounting, lending, and business advisors before making any decision. Additional confidential information may require a signed confidentiality agreement, buyer screening, and Seller approval.