Purchase Price Is Not Everything: How Deal Structure Can Make or Break a Business Sale
Why seller financing, earnouts, escrows, holdbacks, and working capital terms can matter as much as the headline purchase price.
What You Need to Know
A higher purchase price is not automatically the better offer. Structure decides how much the seller actually receives, when they receive it, how much risk they keep after closing, and how likely the deal is to close at all. A $2,000,000 offer can lose to a $1,700,000 offer if the extra money is buried under seller financing, an earnout, vague conditions, and optimism with a signature block. This article translates the language of deal structure into plain English, because most owners are selling a business for the first time and the buyer across the table usually is not.
Why Sellers Over-Focus on the Headline Number
Price is simple, emotional, and memorable. It is the number you repeat at dinner. But the real questions are quieter: what is the seller actually receiving, when, under what conditions, and carrying what risk? Sophisticated buyers know exactly how to use structure to make an offer look stronger than it is. Reading the structure, not just the price, is where business valuation guidance and real advisory earn their fee.
A Plain-English Glossary of the Moving Parts
Before comparing offers, it helps to actually know what the terms mean. Here is the working vocabulary, without the law-school accent.
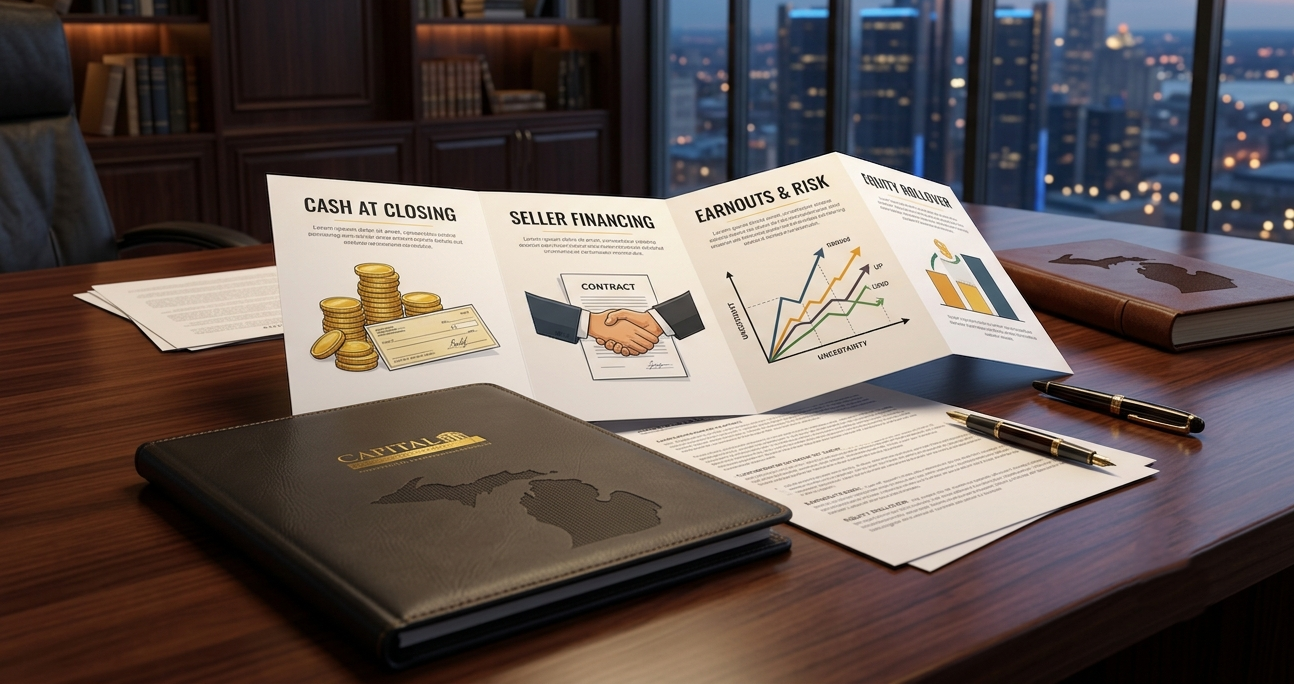
Cash at closing: The money the seller receives the day the deal closes, the cleanest and most certain dollars in any offer.
Seller financing: A loan from the seller to the buyer for part of the price, repaid over time with interest. It bridges gaps and signals confidence, and it puts the seller in the bank’s chair for a few years.
Earnout: Additional price paid later only if the business hits agreed results after closing. It rewards future performance and, handled carelessly, breeds disputes.
Holdback / escrow: A portion of the price set aside after closing to cover specific risks, released later if those risks do not materialize.
Working capital adjustment: A true-up so the business is delivered with a normal level of operating capital, receivables and inventory net of payables, neither stuffed nor stripped.
Asset sale vs. stock sale: Whether the buyer purchases the company’s assets and selected liabilities, or the ownership of the entity itself. The choice drives taxes, liability, and what transfers.
Rollover equity: The seller reinvests part of the proceeds and keeps a minority stake in the new ownership, betting on future upside instead of taking all cash.
Non-compete and consulting: Post-closing agreements where the seller agrees not to compete and often to advise or train; both can carry real allocated value.
All Cash at Closing
An all-cash offer means the seller receives the purchase price at closing, subject to normal adjustments. It is usually the cleanest structure and often the most attractive, assuming the buyer is qualified and the funds are real. All cash slashes post-closing collection risk. It does not erase every risk, since there may still be a working capital true-up or an escrow for representations, but it keeps you from becoming the bank the day after you sell. Note that “all cash to the seller” often means the buyer is using a loan; what matters to you is that the cash arrives at closing, not where the buyer sourced it.
Seller Financing
Seller financing lets the buyer pay part of the price over time. A business might sell for $1,000,000 with $800,000 at closing and a $200,000 seller note paid over several years at interest. It can bridge valuation gaps, satisfy lender requirements, widen the buyer pool, and signal that the seller believes the business will keep performing, which is itself reassuring to a buyer. It also exposes the seller to collection risk if the buyer stumbles. Seller financing is not the villain. It simply needs to be priced with a fair interest rate, documented with a promissory note, secured where possible with a personal guarantee and a lien on the business assets, and understood. Buyers exploring business acquisition financing will often combine a seller note with a bank loan, and when an SBA loan is involved, the lender controls how that seller note is structured.
Earnouts
An earnout pays part of the price later if the business hits agreed results after closing, such as revenue or EBITDA targets. It helps when the seller believes in future performance but the buyer will not pay for that future upfront. The catch is disputes, and earnouts generate more post-closing conflict than any other structure. Who controls operations after closing? What if the buyer changes the marketing, raises prices, cuts a product line, or “strategically repositions” the business, which is corporate language for making everyone nervous? If you accept an earnout, insist on a clearly defined, hard-to-game metric, a defined measurement period, and protections governing how the buyer must run the business during that window. An earnout measured on net profit is easier to manipulate than one measured on revenue, because expenses are easier to move than sales.
Holdbacks and Escrows
A holdback or escrow sets aside part of the price after closing to cover specific risks: working capital, representations and warranties, indemnification, unresolved claims, inventory adjustments, or post-closing obligations. They are common in larger or more complex deals, often in the range of five to fifteen percent of the price held for a defined period. The seller should pin down the amount, the release timing, the conditions, and exactly what could cause the money not to be released, because “we’ll figure it out later” is not a release condition, it is a future argument with your money as the prize.
Working Capital Adjustments
Working capital is the operating capital that keeps the business running, often receivables, inventory, and other short-term assets, net of payables and short-term liabilities. In lower middle market and larger deals, the buyer expects a normal level of working capital delivered at closing, set against an agreed target. Deliver less than the target and the price adjusts down; deliver more and it can adjust up. This topic sounds boring until it quietly moves a six-figure number on the closing statement, at which point it becomes everyone’s favorite topic. Sellers should resist the temptation to strip the business of cash and collect every receivable right before closing, because the working capital peg is specifically designed to catch that.
Asset Sale vs. Stock Sale
In an asset sale, the buyer purchases selected assets and assumes selected liabilities, which limits the buyer’s exposure to the seller’s past and gives the buyer better depreciation. In a stock sale, the buyer purchases the ownership of the company itself, which can be simpler when contracts, licenses, or permits are hard to transfer, and which sellers sometimes prefer for tax reasons. Most small-business and SBA-financed deals are structured as asset sales. The right answer depends on legal, tax, licensing, contract, liability, and financing factors, and on whether the deal is best routed through our larger and complex transaction advisory. The broker does not replace the attorney or CPA here. Doing so would make several malpractice carriers twitch in unison.
Rollover Equity
Rollover equity shows up mostly in larger transactions, especially private equity and strategic deals. The seller reinvests part of the proceeds into the new ownership and keeps a minority stake. If the buyer grows the business and sells again later, that stake can pay off, sometimes handsomely, in what dealmakers call a “second bite of the apple.” It can also tie the seller’s money to future performance and someone else’s execution, in a business they no longer control. It may be attractive, but it is not the same as cash at closing, and it should never be counted as if it were. Rollover is a bet; cash is a result.
Why Financing Contingencies Decide Certainty
A strong-looking offer that depends on financing approval is only as strong as that approval. SBA financing, conventional lending, investor capital, seller notes, and real estate financing all affect timing and certainty. A buyer with a lower price and solid, pre-qualified financing can easily beat a buyer with a big number and no realistic path to the closing table. Certainty is a feature, and good sellers learn to price it. A bird in the hand closes; a bird in the bush retrades.
| Two offers that are not what they look like | |
| Offer A headline | $2,000,000 |
| Offer A cash at closing | $1,100,000 (plus $500k earnout, $400k seller note) |
| Offer A risk profile | $900k depends on future performance and repayment |
| Offer B headline | $1,700,000 |
| Offer B cash at closing | $1,650,000, financing pre-approved |
| Which protects the seller | Often Offer B |
Illustrative. Offer A might pay more if everything goes perfectly for years. Offer B pays nearly all of it now, with far less depending on the buyer’s future execution. “More money later, if” is a different product than “money now,” and a seller should price the difference deliberately, not emotionally.
The Bottom Line
Price gets the attention. Structure determines the outcome. A seller should not reject creativity, but they should read it carefully and understand every term before signing. A complex offer may be perfectly reasonable, or it may be a beautifully wrapped way of saying “you might get paid later if everything goes perfectly.” Either way, it deserves a closer look, and a clear-eyed comparison of net proceeds, timing, and certainty, before anyone celebrates the headline.
About Capital Business Brokerage
Capital Business Brokerage is a Michigan-based business brokerage and M&A advisory firm specializing in the confidential sale and acquisition of privately held businesses across Metro Detroit and the broader Midwest market.